
A New Chapter: Why Australian Retirees Are Downsizing
Across Australia today, retirees are selling their larger long‑term family homes and relocating into lifestyle communities—a move driven by a blending of financial strategy and a desire for a more purposeful, low‑maintenance lifestyle. Many have paid off mortgages on suburban dwellings, and by cashing in on those equity gains, they can buy into an over‑50s or over‑55s lifestyle community outright. At the same time, the property they leave often sells for well above average market value, while homes in lifestyle communities typically cost 75–80 per cent of median local house prices, representing considerable savings.
This trend is particularly amplified among baby boomers accessing their superannuation and looking to free up capital for retirement. Coastal towns such as Portarlington, Point Lonsdale, Paynesville, Mornington, Lorne, and regional New South Wales hotspots like Tuncurry and Forster are seeing a steady stream of retirees making the sea‑change or tree‑change lifestyle shift.
Financial Advantages That Matter
The financial appeal of lifestyle communities often starts with freeing up equity. By selling a large family home, retirees receive a lump sum that lets them buy a manufactured or modular dwelling within a lifestyle community at a fraction of the price in the suburbs. The land‑lease model available in these communities means the retiree owns their home but leases the land. That lease typically includes access to amenities and ongoing site maintenance in a weekly fee. The savings from purchasing at lower prices and avoiding stamp duty in some cases enable retirees to retain capital, secure a comfortable cash buffer, or invest elsewhere.
Another advantage is transparency around fees and the ability to keep any capital gain when the home is eventually resold. Unlike many retirement villages with high entrance or exit fees, several lifestyle communities offer clearer, more favourable financial arrangements that let residents catch the upside when they sell. Residents are often able to carry forward wealth rather than sacrificing it to developers or long‑term contracts.
Lifestyle Rewards: Community and Well‑Being
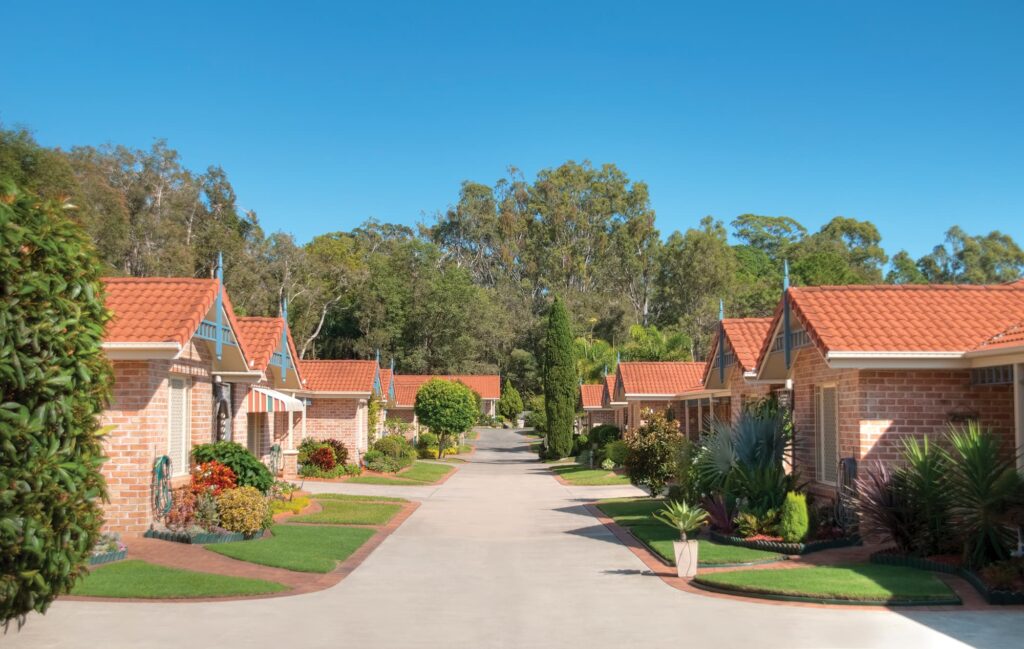
Beyond the financial calculus, retirees are drawn by the sense of belonging and well‑being that lifestyle communities offer. These age‑qualified estates often include landscaped gardens, clubhouses, gyms, pools, wellness centres, walking paths and organised social activities. The optional community life counters social isolation and promotes physical and mental health as people age.
Many operators such as Keyton and Ingenia emphasise a values‑driven approach, focusing on wellbeing, diversity and inclusion across their community offerings. Residents report improved life satisfaction, friendships, and opportunities to engage in hobbies, activities and new social circles.
Moreover, lifestyle communities cater to a more active demographic—nearly 40 per cent of residents continue working part‑time or engaging in hobbies. They are not dormant retirement centres but vibrant residential neighbourhoods tailored for over‑50s, offering flexibility and independence .
Ease, Maintenance, and Resilience
In a large legacy home, daily upkeep—from lawn mowing to roof repairs—can become burdensome as one ages. Downsizing to a single‑level dwelling designed for ease of living significantly reduces maintenance demands, enabling retirees to travel or enjoy leisure without stress. Many communities also provide lock‑up‑and‑leave peace of mind: managers monitor vacant homes when residents are away.
The land‑lease weekly fee structure typically includes grounds upkeep, shared area cleaning, and risk mitigation responsibilities. That predictable cost structure helps retirees plan with confidence, avoiding surprise bills or household chores that can wear down later in life.
The Broader Market Effect and Value Shift
The influx of financially able retirees into lifestyle communities is reshaping local property markets. Because many retirees buy in cash, they are less reliant on mortgages and often close deals quickly. Their presence in coastal or regional towns drives up demand—and, inevitably, prices—in those markets.
Economists now describe a “curse of paradise”: the very towns retirees move into for peaceful living become less affordable to others as property values surge. Long‑time locals and renters may face displacement as retirees bring liquidity into these buying hotspots. But for many retirees, this means their property has also appreciated significantly, so when they sell again or share wealth with family, they reap benefits.
Case Studies: Real People, Real Moves
In Victoria, the couple Cynthia and Colin Bates sold their suburban family home and moved into a Lifestyle Communities estate near Brisbane. They downsized into a smaller home at substantially lower cost and have more disposable income and time. In South Australia, Julie and Kevin Williams moved into an Adelaide hillside retirement village with starting entry costs near $600,000 to gain access to global‑travel focused social groups and care‑forward planning. Their stories echo a broader pattern: retirees selling large homes, cashing in equity, and investing in a more manageable, socially rich environment.
In Queensland, a $100 million development at Hervey Bay targeting over‑50s has been launched, with homes priced from around $565,000. The first phase included pool, spa, gym, cinema, and pickleball courts—enticing amenities designed to attract retirees keen on community and leisure living. In Townsville, an over‑50s lifestyle estate with up to 350 leasehold homes on 99‑year land leases was approved, promising shared wellness facilities and sports spaces.
Buying and Selling in a Lifestyle Community: What You Should Know
Transitioning into a lifestyle community is not always as simple as buying a regular home. Retirement villages and land‑lease communities can involve specific contracts, exit fees, and legal constraints. It’s important to obtain independent legal advice to understand purchase agreements, ongoing fees, resale terms and whether there’s an exit deduction or deferred management fee.
Having clarity on exit terms ensures retirees retain capital gains and avoid unexpected deductions when they eventually move on. Many lifestyle community operators promote transparency and provide resale support through dedicated resale teams, helping owners find new buyers when the time comes.
Social Impact: Embracing Community While Retaining Independence
A defining feature of lifestyle communities is balancing social connection with personal autonomy. Residents live in their own homes, maintain independence, and choose how much they engage in communal life. Activities, clubs, and communal spaces exist, but participation is voluntary. That flexibility gives retirees the best of both worlds: independence and the feeling of belonging whenever they choose.
Despite some reports that tightly gated villages may feel restrictive for vulnerable residents, others see lifestyle communities as empowering environments offering better quality of life, security, and peace of mind.
Why the Trend Will Continue
Demographics and economics suggest this shift will endure. More than 700,000 Australians are expected to retire in the next five years. Baby boomers hold roughly half of Australia’s private wealth. They are accessing funds, downsizing, and using their considerable financial position to influence the housing market. That much wealth entering lifestyle communities will continue to move markets and encourage new development.
Meanwhile, established developers like Lifestyle Communities, Ingenia, GemLife, Stockland and Mirvac are expanding their over‑50s land lease estates nationally. The land‑lease sector has grown into a $12 billion industry and supports over 130,000 residents. That supply expansion, combined with demographic demand, makes it clear retirees will remain major drivers in the market.
The Smart Move for Many Retirees
Selling a high‑equity family home and buying into a lifestyle community provides retirees with a powerful combination of financial flexibility, reduced maintenance, enhanced well‑being, and intentional living. They gain the freedom to explore, the support of a community of peers, and long‑term security—all without sacrificing financial gains or independence.
Whether motivated by lifestyle, liberty, health, or economics, more Australians approaching retirement are choosing to move into lifestyle communities as the smarter, more enriching next chapter of their lives. They are not just downsizing—they are upgrading their retirement experience.